Did you know that 22% of small business loan applicants in 2026 walked away with no funding at all? Often, the biggest barrier isn’t a lack of profit, but the urgent need to clean up business financials for loan approval. You might feel a familiar sense of dread when looking at a backlog of uncategorized transactions or trying to decipher complex bank jargon. It’s frustrating to think that messy records could stand between you and the capital you need to grow. You deserve to feel in control of your numbers, not buried by them.
This guide provides the exact steps to transform your books into a professional, lender-ready package. We’ll walk through how to organize your historical records, simplify complex requirements, and build a roadmap for financial clarity. You’ll learn how to turn chaotic data into the proof lenders require, giving you the confidence to secure the funding your business deserves at a competitive rate.
Key Takeaways
- Understand that lenders prioritize consistency and verifiable data over raw profit when evaluating your business creditworthiness.
- Follow a structured checklist to clean up business financials for loan approval, starting with precise reconciliation of every account.
- Learn how to untangle personal and business expenses to provide underwriters with a clear, accurate view of your operating margins.
- Discover how organized, professional records can unlock more competitive interest rates and higher credit limits for your company.
The Lenders Lens: Why Clean Financials are Your Best Collateral
When you walk into a bank, the lender isn’t just looking at your bank balance. They’re looking for proof of stability. Clean financials are records that are fully reconciled, properly categorized, and verifiable against third-party statements. Lenders perform a rigorous financial statement analysis to decide if your business can handle the weight of more debt. If your books are a maze of missing receipts and “uncategorized” entries, it signals high risk. You must clean up business financials for loan approval to show that your success is predictable, not accidental.
Underwriters often value consistency over a single year of high profit. They want to see that you understand your margins and can weather a sudden downturn. If you’ve fallen behind by several months or even years, a dedicated catch up bookkeeping project can bridge the gap. It replaces the heavy burden of “messy books” with a steady hand that provides clarity to the bank.
The Red Flags That Stop Loan Approvals in Their Tracks
Banks are trained to spot friction. These common errors often cause immediate rejection because they suggest a lack of internal control:
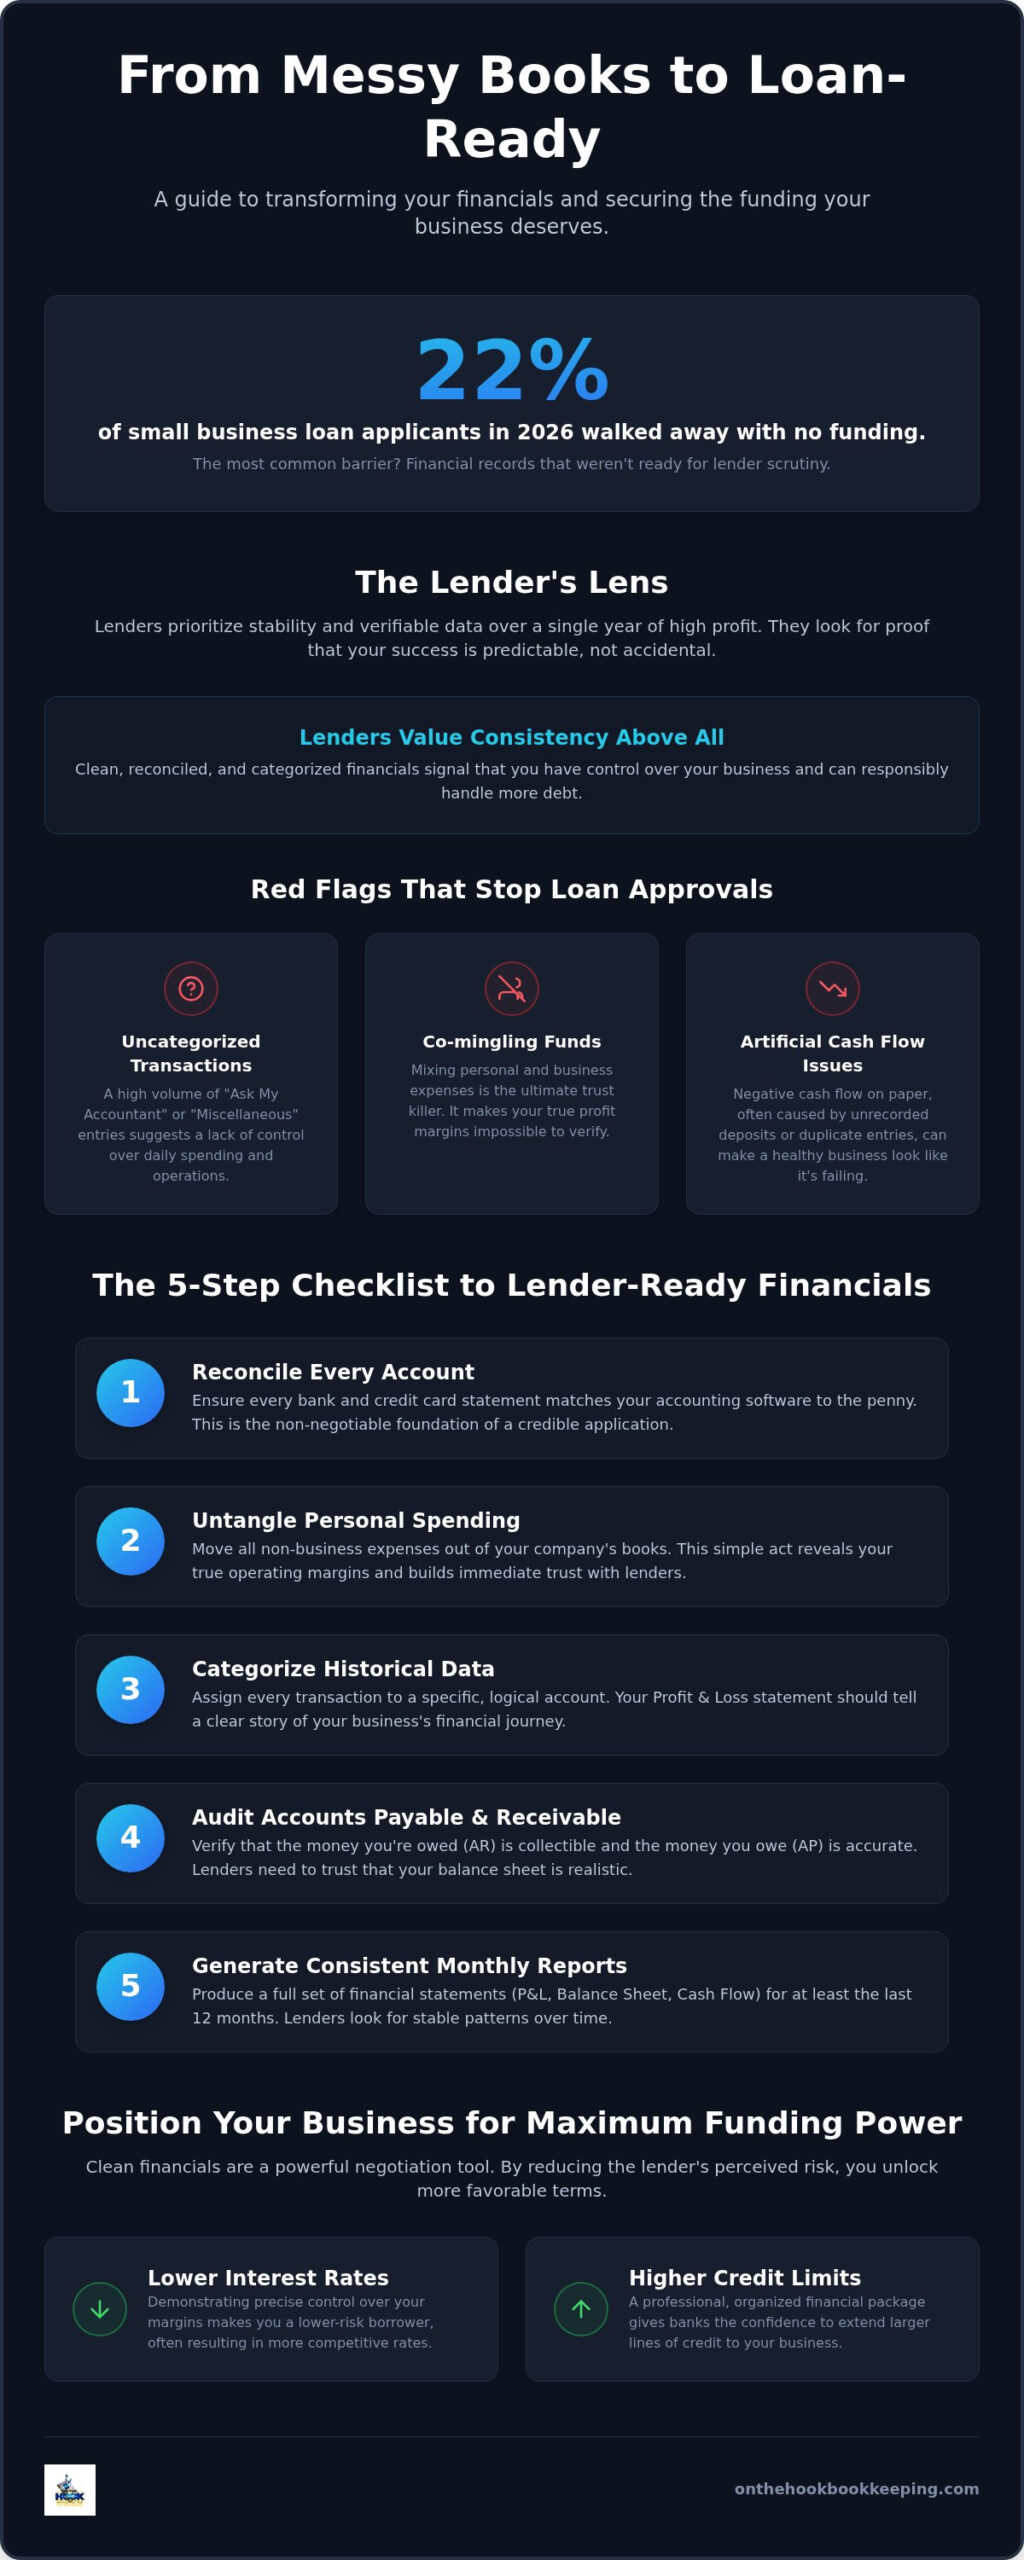
- The “Ask My Accountant” Bucket: A high volume of uncategorized transactions suggests you don’t have a firm handle on your daily spending.
- Co-mingling Funds: Mixing personal and business expenses is the ultimate trust killer. It makes your true margins impossible to calculate and suggests your business isn’t a separate entity.
- Artificial Cash Flow Issues: Negative cash flow on paper is often just a result of unrecorded deposits or duplicate entries. It looks like a dying business when it’s really just an unorganized one.
The 5-Step Checklist to Clean Up Business Financials for a Loan
Preparing for a loan isn’t about hiding flaws; it’s about providing absolute clarity. To clean up business financials for loan approval, you must follow a methodical path that removes every shadow of doubt for the underwriter. Start with these essential steps:
- Step 1: Reconcile every account. Every bank and credit card statement must match your software to the penny. This is the bedrock of a credible application.
- Step 2: Untangle personal spending. Move non-business expenses out of your company view. This reveals your true operating margins and builds immediate trust with the lender.
- Step 3: Categorize historical data. Ensure every dollar has a specific home. Your Profit and Loss statement should read like a clear, logical story of your business growth.
- Step 4: Audit AP and AR. Verify that your Accounts Payable and Receivable are accurate. Lenders need to see that your assets on paper are actually collectible.
- Step 5: Generate monthly reports. Produce consistent financial statements for at least the last twelve months. Lenders look for patterns of stability over time.
Mastering Transaction Categorization for Underwriting Success
Lenders look at “Miscellaneous” expenses with deep suspicion. To them, a large bucket of unclassified costs suggests a lack of internal oversight. Reassign these costs to specific accounts to maintain transparency. Consistency is also vital for payroll. Your financial statements must match your payroll tax filings exactly. Discrepancies here often trigger more questions than they answer. If your current system is cluttered, you might need to fix messy QuickBooks records to ensure your data is lender-ready. Taking the time for a thorough cleanup and catch-up support project now can save you weeks of stress during the application process.
Positioning Your Clean Records for Maximum Funding Power
Clean financials do more than just get you through the door. They’re a powerful tool for negotiation. When you clean up business financials for loan applications, you’re actively reducing the lender’s perceived risk. This visibility often results in more favorable terms, such as lower interest rates or higher credit limits. A bank is much more likely to partner with a “steady hand” who demonstrates precise control over their margins. By presenting a professional year end bookkeeping cleanup, you show that your business is prepared for the scrutiny of the underwriting process.
Moving from a state of catch-up to a state of growth requires consistent visibility. Ongoing monthly reporting ensures that once your books are clean, they stay that way. This shift allows you to make informed decisions based on real-time data rather than historical guesswork. It turns your accounting from a source of stress into a foundation for expansion.
The Role of Professional Cleanup and Catch-up Services
There comes a point where DIY-ing your books becomes a liability rather than a cost-saving measure. Professional small business bookkeeping services handle the heavy lifting of historical organization so you can focus on your primary passion. An expert will help you assemble a complete “Lender Package.” This package typically includes three vital pillars:
- Profit & Loss Statement: A clear view of your revenue and expenses over a specific period.
- Balance Sheet: A snapshot of your company’s assets, liabilities, and equity at a single point in time.
- Statement of Cash Flows: Proof that your business generates enough liquidity to service new debt.
Having these documents reconciled and ready allows you to approach a loan officer with quiet confidence. You’re no longer just asking for money. You’re presenting a verified case for investment.
Secure Your Business Future with Financial Clarity
Winning a lender’s approval is about more than just having a profitable year. It’s about demonstrating that you have a firm, steady hand on the mechanical inner workings of your company. By reconciling every account and untangling personal spending, you remove the friction that often stops funding in its tracks. The decision to clean up business financials for loan approval is a one-time project that unlocks growth for years to come. It replaces financial anxiety with a sense of calm control.
Don’t let messy historical records keep you from the capital you’ve earned. We provide specialized project-based cleanup for loan readiness and are trusted by busy trades and business owners nationwide. Our team delivers the detailed monthly financial reports you need for total visibility and informed decision-making. Get your historical financials lender-ready with our Cleanup and Catch-up services. You’ve done the hard work of building your business; now it’s time to secure the support it deserves.
Frequently Asked Questions
How far back do I need to clean up my financials for a business loan?
Most lenders require two to three years of historical data to evaluate your stability. To clean up business financials for loan approval effectively, you should focus on reconciling the last 24 months of transactions. This depth allows underwriters to see seasonal trends and long-term growth patterns. Having organized records for this period replaces bank anxiety with a sense of calm control.
Can I get a business loan if my QuickBooks records are a mess?
Securing a loan with disorganized records is extremely difficult in the current lending environment. Lenders view messy books as a significant risk factor that suggests a lack of operational oversight. You’ll likely face immediate rejection or predatory interest rates. It’s essential to untangle your accounts and present a professional financial package to show you’re a steady hand worth partnering with.
How long does a professional bookkeeping cleanup typically take?
A professional bookkeeping cleanup for tax season and loan readiness usually spans two to six weeks depending on the complexity of your accounts. This timeframe allows for the meticulous categorization of every historical transaction and the removal of personal spending from business views. It’s a methodical process that transforms a chaotic environment into an orderly foundation. This one-time project is the fastest way to get your business lender-ready.
What is the most important financial statement for a loan officer?
The Debt Service Coverage Ratio, which is derived from your Profit and Loss and Balance Sheet, is often the top priority. Loan officers use this to determine if your cash flow can comfortably handle new monthly payments. They don’t just look for profit; they look for consistency. Providing clean monthly financial reports demonstrates that your business generates enough liquidity to be a safe investment.